Research that shows its sources
Every answer should lead back to the source.
Virtus connects a tax question to the exact page of the public document behind its answer, with the authority status beside it, so the work can be checked and kept.
Question: Did the IRS give more time for the missed QSub elections?
Source-linked answer
The IRS concluded that the taxpayer met the requirements for more time under §§ 301.9100-1 and 301.9100-3 to make QSub elections it had missed for six subsidiaries.1
Complete example. Step 4 of 4: Passage.
Ask in plain words. Nothing is searched until you send it.
The answer names the ruling it relies on, with a numbered citation.
Select the citation and the source opens beside the answer.
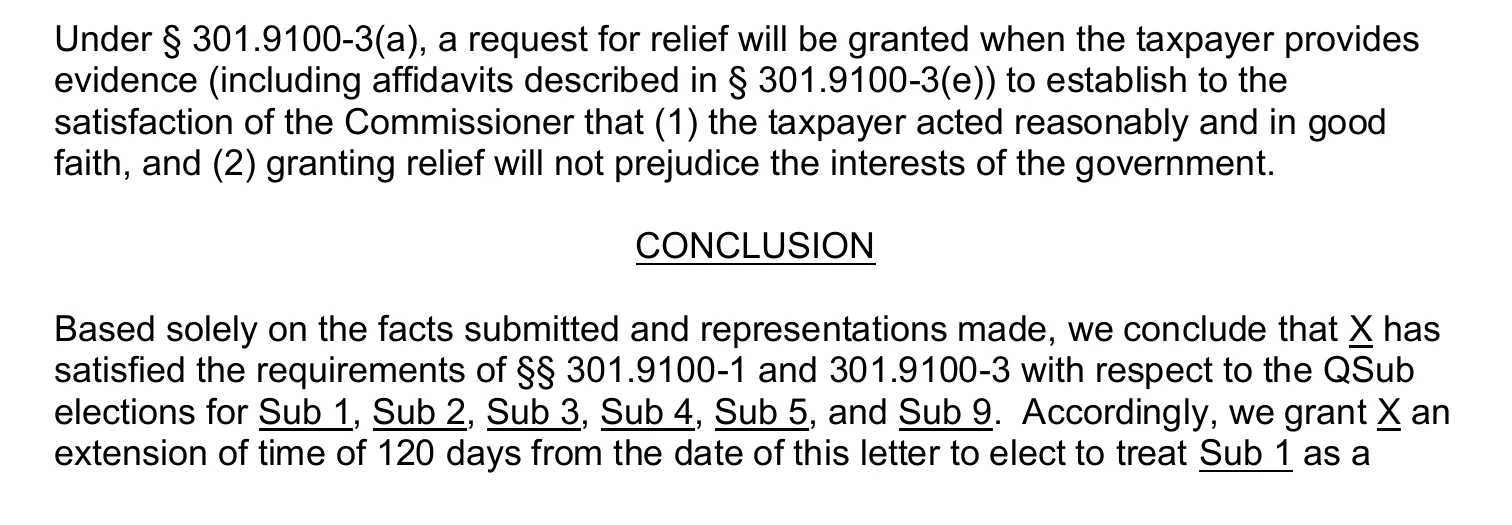
The exact page-four passage is marked, with the ruling’s authority beside it.
The exact page-four passage is marked, with the ruling’s authority beside it.
Stage 01: The source
The original stays the original.
A citation is only as good as the page behind it. Virtus keeps the publisher’s document distinct from the text it searches, and marks the quoted passage where the publisher put it.
Conclusion
Based solely on the facts submitted and representations made, we conclude that X has satisfied the requirements of §§ 301.9100-1 and 301.9100-3 with respect to the QSub elections for Sub 1, Sub 2, Sub 3, Sub 4, Sub 5, and Sub 9.[1]
Stage 02: The limits
When the library has no support, it says so.
A ruling binds only the taxpayer who asked for it, and a library has edges. Virtus shows the authority status with the passage, and when nothing it holds supports the question, the answer is “no cited answer” rather than a guess.

Searchable collections
Whole documents, each kept with its original file.
- IRS written determinationsInternal Revenue Service
- IRS revenue proceduresInternal Revenue Service
Searchable sections
Current Title 26 text, cited by section.
- Internal Revenue CodeOffice of the Law Revision Counsel
- Treasury regulationsElectronic Code of Federal Regulations
Planned
In the product plan. Not in the library today.
- U.S. Tax CourtUnited States Tax Court
Stage 03: The work
Carry the trail with the work.
Mark the passage you rely on in one of four colours and download a working copy with standard PDF annotations. The original stays as the publisher issued it, and the conversation stays with its sources in a private project.
IRS Private Letter Ruling 202627005 · Released July 2, 2026 · Page 3
Private letter ruling · Nonprecedential
Section 1361(a)(1) provides that the term “S corporation” means, with respect to any taxable year, a small business corporation for which an election under § 1362(a) is in effect for the taxable year.
Solutions
One trail. Different work to do.
Resources